Money Supply
Summary
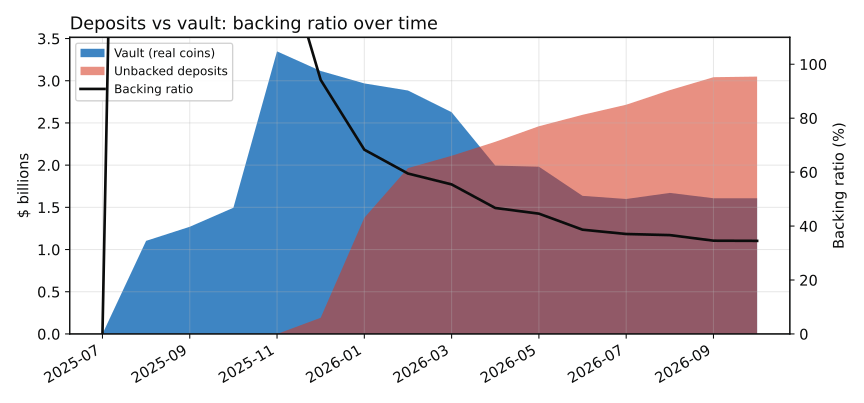
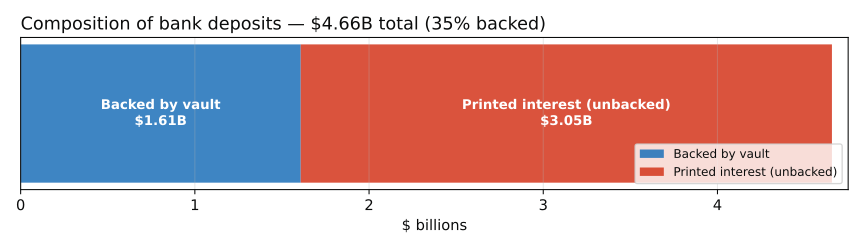
Bank deposits total $4.66B, but the vault holds only $1.61B in real coins — the money supply is 35% backed. The gap was created by interest that was printed rather than funded. At the current interest rate (0.5% per day), the money supply still grows by about $1.3M per day after taxes.
1. Backing over time
Every deposit is a promise the bank pays you in real coins. The chart below compares the vault (real coins the bank actually holds) against total deposits. The two were briefly equal in late 2025 — since then, interest payments have created deposit money faster than real coins entered the vault.
2. What the deposit stock is made of
Of the $4.66B owed to depositors, $1.61B is covered by real coins. The remaining $3.05B exists only as printed interest that was never backed by anything.
3. Printing versus sinks versus the real economy
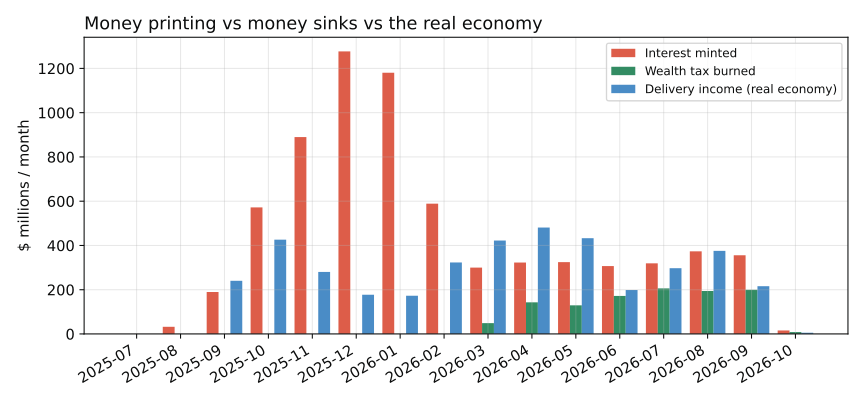
Each month the bank mints interest, the wealth tax burns money back, and the real economy pays out delivery income. Interest minted has been of the same order as everything the entire delivery workforce earns — passive capital earns as much as active labour.
4. Real coins in and out of the vault
Real coins enter the vault when players deposit earnings, when loan repayments come back, and when the treasury funds the bank; they leave when players withdraw cash, take out loans, and when subsidies are paid. The histogram below breaks each month down by category, with the net flow overlaid. Deposits of real coins outran outflows through 2025; from December 2025 outflows caught up.
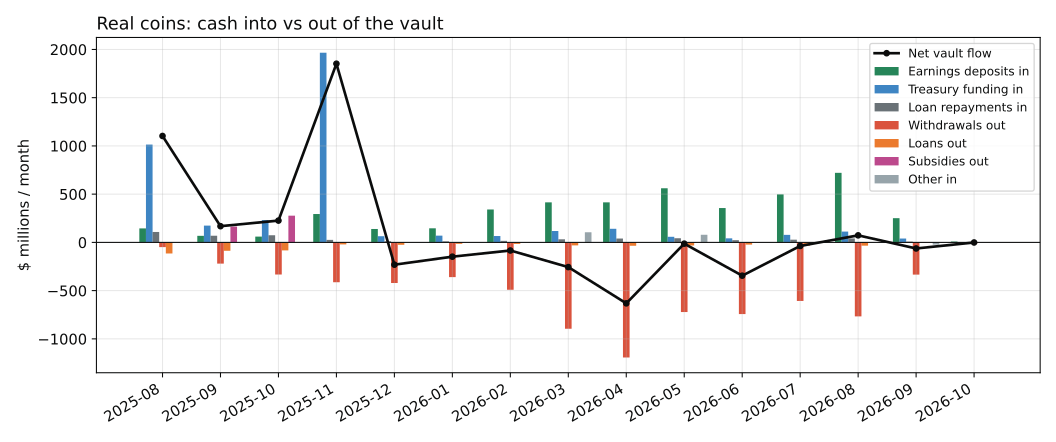
| Month | Net | Earnings deposits in | Treasury funding in | Loan repayments in | Withdrawals out | Loans out | Subsidies out |
|---|---|---|---|---|---|---|---|
| 2026-05 | $-13.0M | $561.0M | $58.0M | $43.0M | $722.0M | $32.0M | $0.0M |
| 2026-06 | $-345.0M | $356.0M | $42.0M | $23.0M | $743.0M | $23.0M | $0.0M |
| 2026-07 | $-37.0M | $498.0M | $78.0M | $28.0M | $607.0M | $34.0M | $0.0M |
| 2026-08 | $73.0M | $721.0M | $112.0M | $41.0M | $767.0M | $34.0M | $0.0M |
| 2026-09 | $-63.0M | $251.0M | $40.0M | $8.0M | $334.0M | $5.0M | $0.0M |
| 2026-10 | $-1.0M | $9.0M | $1.0M | $0.0M | $11.0M | $0.0M | $0.0M |
5. Projections at the current interest rate
Projecting forward 12 months, assuming the deposit base changes only through minted interest and the wealth tax (both at recent observed rates):
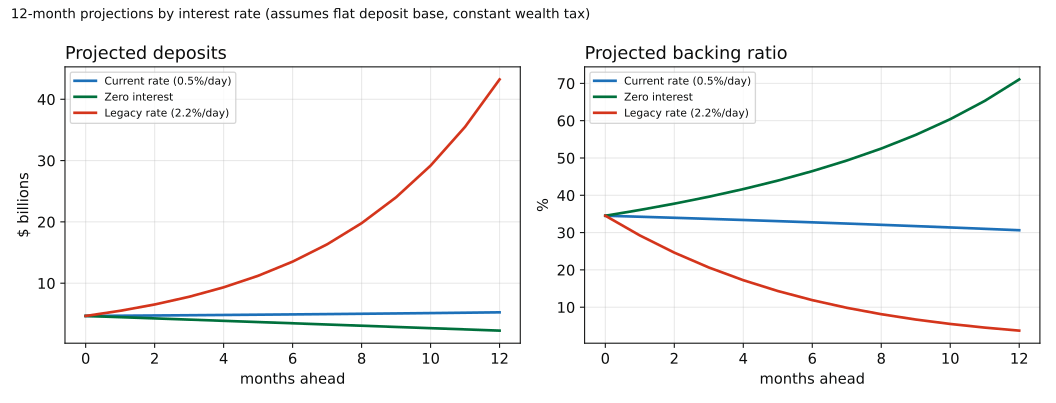
| Scenario | Daily rate | Deposits after 12 months | Backing after 12 months |
|---|---|---|---|
| Current rate | 0.5% | $5.28B | 30% |
| Zero interest | 0% | $2.26B | 71% |
| Legacy rate | 2.2% | $43.95B | 4% |
6. Assumptions and limits
- The deposit base changes only through minted interest and wealth tax. Large withdrawals, deposits of cash, and loans are not modelled — in aggregate they have netted to roughly zero per month.
- Minted interest scales with the deposit base and the rate, with an offline/threshold decay factor of 0.341 calibrated from observed payments.
- The wealth tax burn is held at its recent monthly level ($199.6M per month).
- The vault is held flat: cash deposits and withdrawals net to approximately zero monthly, and neither interest nor the tax routes coins into the vault.
- These are projections, not guarantees — the Bank can change the rate at any time.
7. Analysis
Why only 35% is backed. Interest on deposits was paid by creating new deposit money rather than from real income. Cumulative printed interest now stands at $7.05B — more than the entire deposit stock once over — while the vault holds $1.61B.
Is the bank broke? No. The bank is the money issuer: withdrawals are always payable because new cash can be issued. The binding constraint is not solvency but inflation — every unbacked deposit competes with real delivery income for the same goods and prices.
Is the treasury healthy? Yes. Treasury revenue and expenses have tracked each other closely month to month, and every treasury payout is floor-guarded. The imbalance lives entirely in the banking side.
Passive versus active income. At the current rate, deposit interest still pays out of the same order as the whole delivery workforce's earnings ($238.2M per month in interest versus recent delivery income of $200–430M per month). Passive capital income at that scale is an economy-level policy question, which is why the rate was cut and why funded-only interest is being considered.